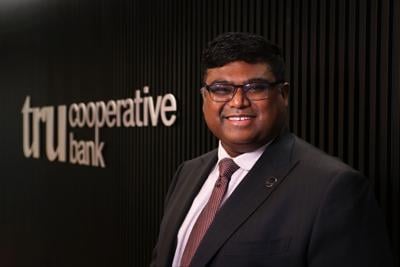

As mortgage products become more complex and Canadians face affordability pressures, borrowers should get as much information as possible when choosing a mortgage lender. It is important to look not just at mortgage rates, but factors such as terms for breaking a mortgage early, refinancing, paying off a mortgage early or switching lenders at renewal, says Sundar Ramanathan, senior vice president of pricing & national expansion, at Tru Cooperative Bank, based in Langley, B.C.
Canadians may be overlooking important—and potentially costly—factors when weighing their mortgage options
For many Canadians, deciding on a mortgage comes down to one number: the rate.
Whether they’re buying a new home or heading into a mortgage renewal, people may spend weeks comparing rates, using online calculators, consulting mortgage brokers and weighing offers from lenders, all to determine their monthly payment.
“The questions are mostly around rates because they’re so visible,” says Sundar Ramanathan, senior vice-president of pricing & national expansion, at Tru Cooperative Bank, based in Langley, B.C. “A mortgage is a very important decision because it’s the largest financial obligation most Canadians will have in their lives. So, every dollar counts, especially in today’s inflationary environment.”
While rates make the headlines, there’s an important detail in the fine print: The lowest rate doesn’t always mean the best mortgage.
“Everybody has a budget in mind, and they see the rate first, but other major factors are often missed,” says Ramanathan. “The rate is definitely important, but it is only one piece of the puzzle.”
The other pieces can end up being costly. Two mortgages may have nearly identical rates but vastly different terms for breaking a mortgage early, refinancing or switching lenders at renewal. “Once people start asking the right questions, they start to realize that not all mortgages are the same,” says Ramanathan.
The bigger mortgage picture
Life doesn’t always go according to plan. People move, change jobs, start families, downsize, separate or relocate. These major life events could mean selling a home and discharging, or “breaking,” the mortgage before the term is up. This can trigger a prepayment penalty.
In some cases, a mortgage that offers greater flexibility can save borrowers more money over the long term than one with a slightly lower rate.
“If you want to break a mortgage and sell the property, whether you have a fixed or variable rate really matters,” says Ramanathan.
Depending on the lender and mortgage terms, a variable-rate mortgage may carry a penalty based on three months’ interest. Some fixed-rate mortgages may carry the greater of three months’ interest or an interest rate differential, which reflects the difference between the mortgage rate and a comparable current rate.
“It’s not a small amount. It could be in the tens of thousands of dollars, especially if you’re in an expensive real estate market like British Columbia or Southwestern Ontario,” says Ramanathan.
Whether borrowers choose a variable or fixed rate, the key is to understand how potential penalties are calculated upfront. Even if it’s uncomfortable to think about the “what-ifs,” Ramanathan says doing so can help prevent expensive surprises later.
Investors may approach a house as a financial instrument and have an exit strategy, Ramanathan says, but homeowners often have very different goals. “When it’s a home, it’s sentimental. All you care about is, ‘Can I afford this beautiful house? Is it a stretch, or can I keep my monthly payments under control?’ They don’t think about the prepayment penalty.”
Flexibility can also be important when moving. Depending on the mortgage terms, some lenders allow borrowers to transfer their existing mortgage to a new property, a feature known as porting. This may allow borrowers to avoid the penalty for breaking their mortgage.
“If you’re in a profession where you’re mobile and may need to move provinces, is the rate the most important consideration? Or do you need the flexibility to keep your mortgage and not end up paying a $20,000 or $30,000 prepayment penalty if you get transferred or take a job in a different province?” says Ramanathan.
Flexibility matters during the mortgage term, but borrowers should also consider what happens when it ends. Many Canadians spend months researching their first mortgage, but when the term is up, they simply sign their renewal offer without exploring alternatives or seeking advice.
However, rising housing costs over the last few years have changed that equation. Borrowers who locked in low rates are now facing significantly higher payments at renewal. “If you locked in at 1.5% to 2% in 2021 and it’s now 4.5%, that’s a payment shock and a stress for an average household,” says Ramanathan. “A mortgage renewal shouldn’t just be a conversation about the rate. It’s an opportunity to look at your broader financial picture with an advisor, whether that means extending your amortization to lower your payments or refinancing to consolidate higher-cost debt and ease your monthly cash flow.”
As mortgage products become more complex and Canadians face affordability pressures, the right advice can help borrowers see the bigger picture. It’s a need Ramanathan is seeing as Tru Cooperative Bank expands its Mortgage Broker Centre beyond B.C., bringing its broker-focused mortgage business to more Canadians. Mortgage professionals can help borrowers weigh the trade-offs between cost, flexibility and long-term financial goals.
“Finding the right broker, advisor and financial institution is an important part of the process,” says Ramanathan. “It’s no longer about looking for the lowest rate. It’s about finding a good, knowledgeable advisor who will guide you and provide a comprehensive solution.”